Business
Modernizing Legacy Applications: A Serverless Approach for Indian Enterprises


You’re aiming to modernize legacy applications for Indian enterprises, and adopting a serverless approach is the key. This strategy slashes costs by up to 80% while enhancing scalability and agility, ensuring you stay competitive. With options like AWS Lambda and Amazon Aurora, you can simplify management and seamlessly integrate with emerging technologies like AI and IoT. Shift legacy systems using tools such as Babelfish, enabling smoother migrations without extensive refactoring. Refactor to microservices for increased flexibility and engage cross-functional teams to align goals. Investigate deeper to explore these transformations and reshape your enterprise’s digital landscape efficiently.
Challenges in Legacy Systems
In the domain of modern enterprise technology, legacy systems present a formidable challenge. You’re faced with high maintenance costs, as enterprises see a 15% yearly budget increase just to keep these systems running. This financial strain makes it difficult to allocate resources for innovation.
Additionally, legacy systems have limited scalability and agility, bottlenecking your growth potential and causing you to miss critical opportunities in a fast-evolving market. Security vulnerabilities further compound these issues, exposing your organization to costly data breaches and the risk of regulatory fines and reputational damage.
The lack of skilled professionals who can navigate outdated technologies adds another layer of complexity. Finding expertise to maintain and upgrade these systems is like trying to source parts for classic cars—time-consuming and costly.
That’s where a serverless app modernization company in India, or an AWS serverless consulting company in India, can help. By engaging a serverless consultant in India, you can strategically shift from these cumbersome legacy systems to scalable, secure, and cost-effective solutions.
This approach not only mitigates technical debt but also positions your enterprise to seize new opportunities with agility and confidence, ensuring your business remains competitive in today’s digital landscape.
Benefits of Going Serverless
Why should Indian enterprises consider a serverless approach? Shifting to serverless architecture brings substantial benefits, particularly regarding cost savings and efficiency. You can cut costs by 50-80% since you’ll eliminate expenses related to unused server capacity and drastically reduce server management overheads. The pay-per-use model guarantees you only pay for what you use, making your operations more cost-effective and predictable.
Moreover, serverless solutions automatically scale to meet real-time demands, aligning with your business goals and enhancing performance metrics. This scalability guarantees your applications remain responsive, even as user demand fluctuates, offering a seamless experience that aligns with modern user expectations in serverless UI engineering services in India.
Serverless architecture also simplifies application management, allowing developers to concentrate on refining individual functions instead of managing infrastructure. This focus accelerates development cycles, enabling you to deliver new features and updates faster, staying competitive in the market.
Additionally, integrating emerging technologies like AI and IoT becomes seamless, empowering your enterprise to innovate rapidly. This adaptability allows you to respond effectively to market changes, keeping your business at the forefront of technological advancements in India’s dynamic business landscape.
Key Tools and Technologies
As Indian enterprises recognize the advantages of a serverless approach, understanding the key tools and technologies becomes fundamental in leveraging these benefits. AWS Lambda stands out by allowing you to run code without provisioning servers, thereby enhancing scalability and reducing operational complexity. This tool is vital for seamlessly modernizing legacy applications into a cloud-native environment.
Consider Amazon Aurora, a fully managed relational database service. It’s compatible with MySQL and PostgreSQL, providing high performance and cost-effectiveness, essential for your cloud strategy. Babelfish for Aurora PostgreSQL further simplifies conversion by supporting T-SQL commands, making Microsoft SQL Server application migration seamless without extensive code refactoring.
To streamline data migration, leverage SQL Server Integration Services (SSIS). It supports various data transformation tasks, vital for Babelfish-enabled databases. Opt for serverless databases like AWS DynamoDB to automatically scale with dynamic workloads without the burden of server management.
| Tool/Technology | Functionality | Benefit |
| AWS Lambda | Run code without servers | Enhances scalability, reduces complexity |
| Amazon Aurora | Managed relational database service | High performance, cost-effective |
| Babelfish for Aurora | Migration support for Microsoft SQL Server apps | Reduces code refactoring needs |
Utilizing these strategic tools guarantees a robust and efficient conversion to a serverless architecture.
Database Modernization Strategies
Database modernization strategies are essential for Indian enterprises seeking to harness the full potential of cloud-native solutions. Shifting from traditional SQL databases to cloud-native options like Amazon Aurora or serverless databases such as AWS DynamoDB can greatly enhance scalability and performance.
These modern solutions eliminate the constraints of on-premises systems, enabling your enterprise to adapt to increasing data demands seamlessly.
To facilitate a smoother data migration, leverage tools like SQL Server Integration Services (SSIS) and Babelfish. These tools guarantee compatibility between Microsoft SQL Server and PostgreSQL, minimizing the need for extensive refactoring.
This strategic move not only saves time but also reduces the risk of data migration errors.
Embracing managed database solutions cuts maintenance costs and licensing fees while boosting reliability with automated patching and support from cloud infrastructure.
Replatforming legacy databases onto cloud-based architectures allows you to tap into advanced capabilities and easily integrate emerging technologies.
Steps for Successful Transition
Shifting to a serverless architecture requires a strategic approach to guarantee a seamless changeover. Start by evaluating your existing legacy infrastructure to pinpoint inefficiencies, scalability limitations, and security risks. This evaluation will inform a tailored modernization strategy that addresses your specific needs.
Next, select a suitable serverless architecture, such as AWS Lambda or Google Cloud Functions. These platforms will help you eliminate the burden of server management and substantially reduce operational costs by 50-80%.
As you shift, gradually refactor monolithic applications into microservices. This approach enhances agility and responsiveness, allowing independent deployment and scaling of application components.
Implement a robust monitoring system, like AWS CloudWatch, to track performance metrics. This confirms the reliability of serverless functions both during and after the changeover. Monitoring is essential to swiftly identifying and resolving any issues that may arise.
Form a cross-functional team consisting of technical and business stakeholders. Their collaboration will align your modernization goals with broader business objectives, guaranteeing that the changeover supports your enterprise’s strategic vision.
Frequently Asked Questions
What Is Modernizing Legacy Systems?
You modernize legacy systems by updating outdated applications to improve performance, scalability, and security. Shift to microservices and cloud infrastructure to reduce technical debt, streamline workflows, enhance user experience, and maintain competitiveness in today’s fast-paced market.
How APIS Can Modernize Legacy Systems?
Imagine APIs as bridges connecting old castles (legacy systems) to bustling cities (modern applications). You enable seamless data flow, enhance scalability, and reduce costs, letting legacy systems thrive in a dynamic, cloud-native world.
Which Serverless Option Is Based on Developing?
You’re focusing on AWS Lambda and Azure Functions as serverless options. They let you develop code without handling infrastructure. Their integration capabilities and microservices support offer strategic advantages for scalable, efficient, and cost-effective application development.
Conclusion
As you begin modernizing legacy applications, a serverless approach reveals transformative potential. Imagine accessing unparalleled scalability and efficiency, but here’s the twist—it’s not just about technology. It’s about positioning your enterprise at the forefront of innovation. The tools and strategies discussed are your compass. Will you seize this opportunity to redefine your IT landscape? The choice is yours, and the future of your enterprise hinges on this pivotal decision. What’s your next move?
Business
Households Photograph Valuables to Speed Up Home Insurance Claims
Households are photographing their valuables and keeping simple home inventories to make insurance claims faster and less stressful when something.

Households are photographing their valuables and keeping simple home inventories to make insurance claims faster and less stressful when something goes wrong. Insurers say claims for theft, fire and water damage are settled more quickly when customers can show clear photographs of items, rooms and serial numbers, together with receipts or valuations where they exist. A basic inventory need not take long: walking through each room with a phone camera, opening cupboards and recording key items creates a useful record in under an hour. Photographs stored securely online remain available even if the phone itself is lost or damaged in the incident being claimed for. Loss adjusters add that images of rooms in normal condition also help establish the overall standard of furnishings, which supports fair settlement for items that cannot be individually evidenced. High value items such as jewellery, watches and instruments may need specified cover or professional valuations, and creating an inventory often prompts owners to check whether their current policy limits are realistic. Brokers encourage households to refresh the record after major purchases and home improvements. What begins as a simple photographic habit can therefore reveal underinsurance early, when it is still cheap and easy to correct.
What the Evidence Shows
The practice is especially valuable for items whose worth is hard to prove later, including inherited pieces, collections and specialist equipment used for hobbies or home working. Photographing hallmarks, model plates and any distinguishing marks gives insurers concrete detail that a verbal description cannot match. Families are also advised to keep digital copies of instruction manuals and warranty documents in the same folder, creating a single, organised evidence pack. During a claim, this preparation shortens the back and forth of requests for proof, helping households replace essentials sooner at a difficult time. Insurers stress that an inventory does not replace adequate cover, and contents sums should still reflect the full cost of replacing everything, not only the items photographed. Renters benefit as much as owners, since their belongings are equally vulnerable and sometimes wrongly assumed to be covered by a landlord’s policy. Community safety groups have begun including inventory sessions in wider home protection advice, alongside locks and alarms. In an era when most people already carry a capable camera, the small effort of documenting belongings stands out as one of the simplest ways to strengthen a household’s financial resilience against unexpected loss. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following photographing valuables insurance claims say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by photographing valuables insurance claims are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with photographing valuables insurance claims will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
Business
Local Credit Unions Expand Low-Cost Loans for Home Repairs
Local credit unions are expanding small, lower cost loan schemes for essential home repairs, aiming to help members fix boilers, roofs and damp.
Local credit unions are expanding small, lower cost loan schemes for essential home repairs, aiming to help members fix boilers, roofs and damp problems without turning to expensive short term credit. The community owned lenders say repair loans are among their most requested products, because a failed heating system or leaking roof cannot safely wait while a household saves. Many schemes let members borrow modest amounts with repayments matched to paydays, and some offer a short savings period first so borrowers build a small buffer alongside the loan. Credit unions assess affordability individually and often know their members personally, which staff say leads to more realistic repayment plans than automated decisions alone. Housing charities support the expansion, noting that prompt repairs prevent minor faults becoming major damage and protect health, particularly for older residents and families with young children. Funding for the schemes comes from member deposits, social investment and, in some areas, council partnerships targeting cold homes. Managers stress that credit unions must lend responsibly like any regulated lender, and not every application will succeed, but unsuccessful applicants are usually signposted to grants or advice rather than left without any help.
What the Evidence Shows
Members who used the repair loans say the speed of a local decision mattered almost as much as the interest rate, especially when a boiler failed during cold weather. Credit unions report that repayment rates on repair lending are strong, which they attribute to careful affordability checks and borrowers’ determination to protect their homes. Some schemes now bundle loans with free energy advice, helping households reduce bills after the repair through insulation, heating controls or tariff checks. Contractors working with the programmes are vetted for fair pricing, protecting borrowers from inflated quotes when they are under pressure to act quickly. Advisers still recommend checking for grants first, particularly for disabled residents or those on low incomes, since grant funding does not need repaying. Where no grant applies, comparing the total repayment on a credit union loan with credit cards or doorstep lenders usually shows a substantial saving. Sector leaders hope the expansion demonstrates a wider role for community finance, providing patient, fairly priced lending rooted in local knowledge at a time when many households feel distant from large financial institutions. Reporting and analysis from sources such as World Bank track the same developments, and specialists following credit union home repair loans say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, credit union home repair loans matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for credit union home repair loans hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
Business
Families Compare Home Insurance Renewals With a Simple Checklist
Families are using a simple checklist to compare home insurance renewals, after years in which many policies simply rolled over at higher prices.
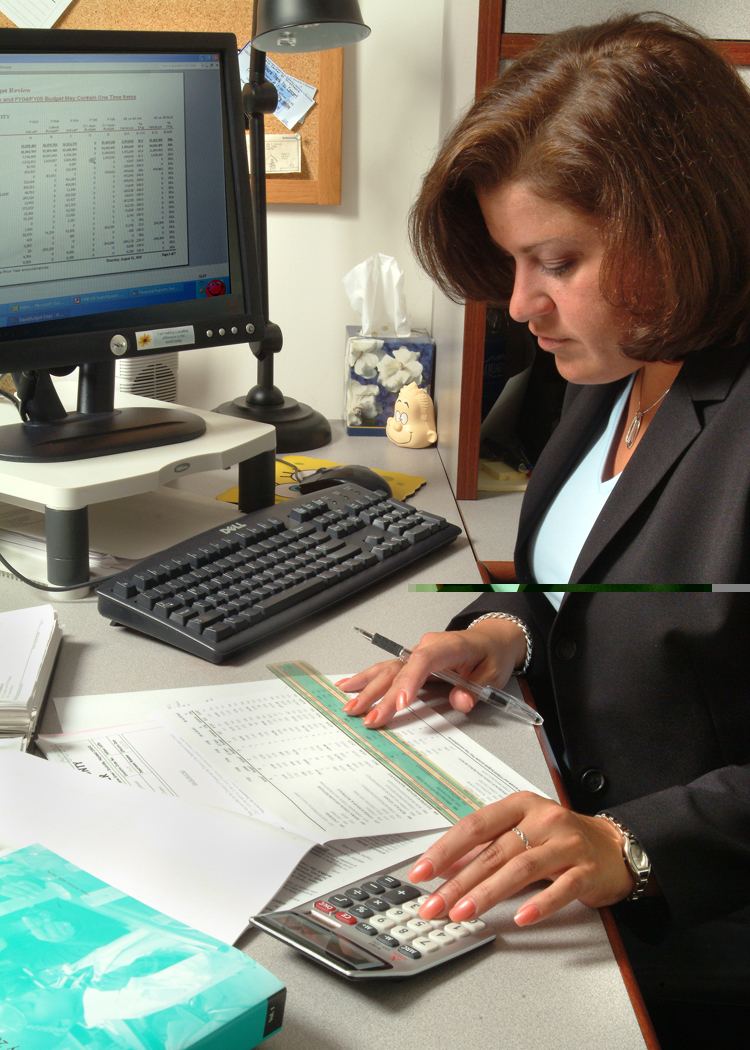
Families are using a simple checklist to compare home insurance renewals, after years in which many policies simply rolled over at higher prices with little scrutiny. The checklist starts with the basics that most affect a claim: whether the rebuilding cost estimate for the home is still realistic, whether the contents total reflects recent purchases, and what excess would actually have to be paid if something went wrong. It then prompts a look at exclusions and limits for bicycles, electronics taken outside the home, and water damage, which are common sources of disappointment. Consumer advisers say comparing policies on cover rather than price alone takes only a little longer, and prevents the false economy of a cheap policy that fails precisely when a household needs it most, after a burglary, fire, or serious leak. For many people, that kind of steady, practical improvement matters more than dramatic announcements or bold promises about the future.
What the Evidence Shows
Timing matters too. Families who begin comparing a few weeks before renewal, rather than on the final day, report calmer decisions and better quotes, because insurers price differently depending on how far ahead a policy is arranged. The checklist includes keeping a note of the renewal date in a shared calendar, storing policy documents where both adults can find them, and photographing valuable items and receipts as evidence for any future claim. Advisers also remind households to tell insurers about changes such as building work, a new lodger, or working from home with expensive equipment, since undeclared changes can complicate claims. Renewal will rarely be enjoyable, but with a shared checklist it becomes a short annual routine that keeps cover honest, prices competitive, and surprises to a minimum. Looking ahead, the organisations involved say they will publish what they learn, including the parts that did not work as hoped, so others can benefit from the experience. Reporting and analysis from sources such as World Bank track the same developments, and specialists following a simple checklist for home insurance renewals say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, a simple checklist for home insurance renewals matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for a simple checklist for home insurance renewals hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.

Households Photograph Valuables to Speed Up Home Insurance Claims

Local Credit Unions Expand Low-Cost Loans for Home Repairs

Families Compare Home Insurance Renewals With a Simple Checklist

Shoppers Return to High Streets for Value as Online Prices Are Compared in Store

Homeowners Compare Insurance Excess Levels Before Renewal Deadlines

Families Track Subscriptions In A Shared Notebook To Cut Waste

Developers Adopt Review Checklists That Catch Accessibility Faults Early

14 ExtraTorrent Proxy | Unblock All Extratorrents Sites

Facebook VIP Cover Photos

Jay Bhim Bio For Instagram

क्षत्रिय Bio For Instagram in Hindi

How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide

Instagram Bio Marathi

Islamic Bio For Instagram

 Tech2 years ago
14 ExtraTorrent Proxy | Unblock All Extratorrents Sites
- Facebook Bio2 years ago
Facebook VIP Cover Photos
- Instagram Bio2 years ago
Jay Bhim Bio For Instagram
- Instagram Bio2 years ago
क्षत्रिय Bio For Instagram in Hindi
- LATEST NEWS2 years ago
How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide
- Instagram Bio2 years ago
Instagram Bio Marathi
- Instagram Bio2 years ago
Islamic Bio For Instagram
- Tech2 years ago
Socialmediagirls Forums: A Great Way to Find New Friends