Business
Families Track Subscriptions In A Shared Notebook To Cut Waste
Families are tackling subscription creep by listing every recurring payment in a shared notebook or simple household spreadsheet, after realising.

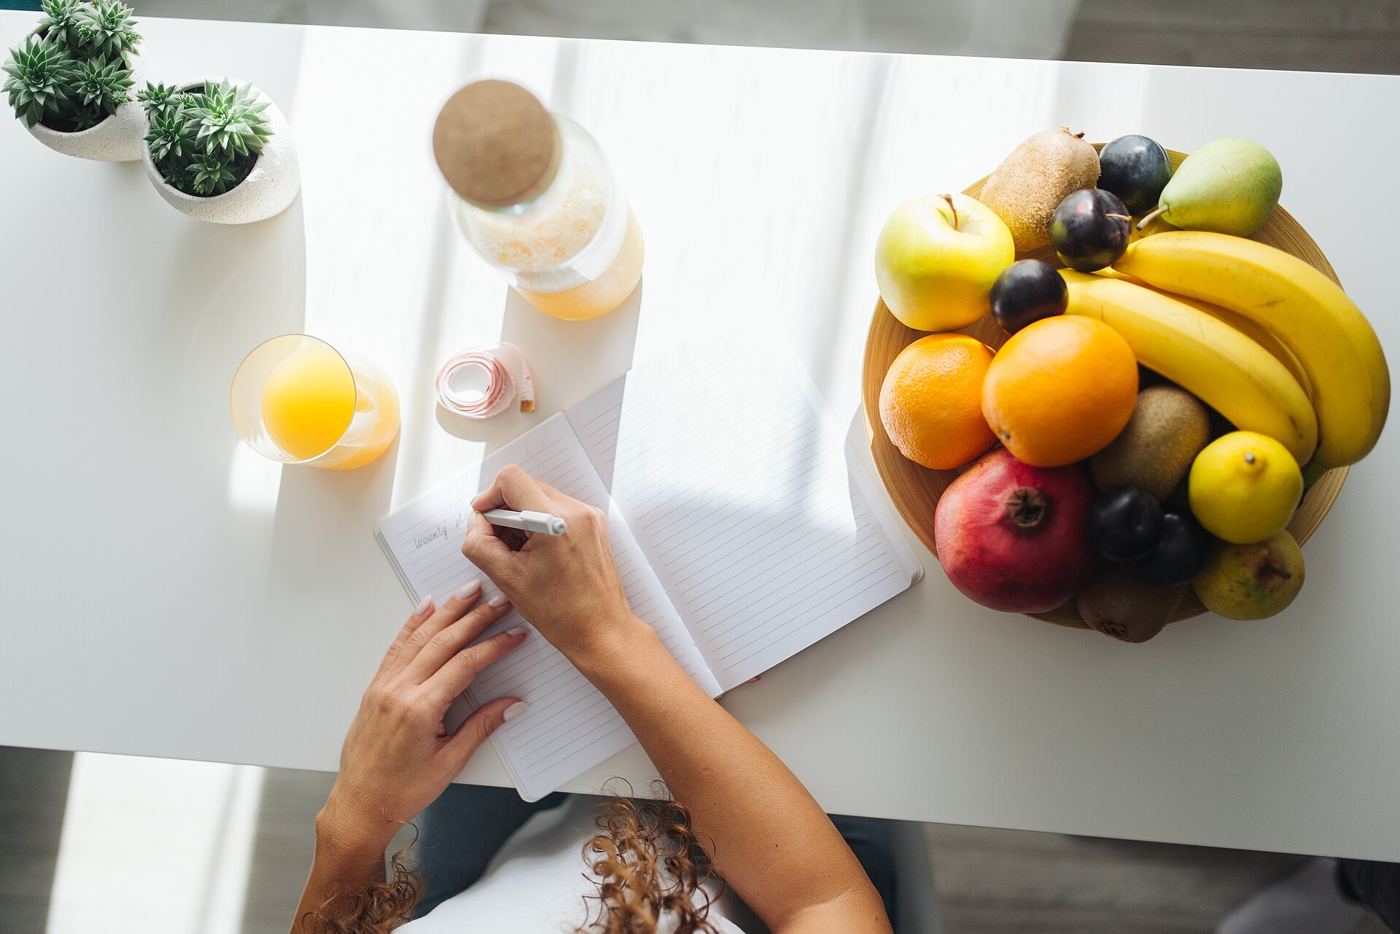
Families are tackling subscription creep by listing every recurring payment in a shared notebook or simple household spreadsheet, after realising how many small monthly charges accumulate unnoticed. Streaming services, apps, cloud storage, delivery schemes and memberships often begin with free trials or introductory offers, then renew quietly at full price. A written register showing the cost, renewal date and main user of each service makes the total visible and prompts an honest conversation about what is genuinely used. Households report cancelling duplicates, rotating entertainment services month by month, and choosing family plans where they offer real value. The exercise also surfaces forgotten commitments such as extended warranties and charitable donations that people may wish to keep, adjust or stop deliberately rather than by accident. Visibility, rather than strictness, is the main benefit. Many are surprised to find the combined total rivals a major household bill.
What the Evidence Shows
Money advisers suggest reviewing the list quarterly, setting calendar reminders a few days before annual renewals, and checking whether student, employer or bundled discounts apply. Paying annually can be cheaper for services a family definitely uses, but only when the upfront cost does not strain the monthly budget. Shared accounts should follow provider rules, and password managers help keep access secure when memberships change. Families with children find it useful to agree a small number of chosen services together, teaching younger members that digital goods still carry real costs. Any money saved can be redirected immediately to a named goal, such as a holiday fund or emergency savings, so the benefit feels concrete rather than theoretical. The simple habit of writing payments down transforms dozens of invisible charges into a short, manageable list that the whole household understands and controls. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following tracking household subscriptions to cut wasteful spending say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by tracking household subscriptions to cut wasteful spending are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with tracking household subscriptions to cut wasteful spending will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
Business
Homeowners Compare Insurance Excess Levels Before Renewal Deadlines
Homeowners approaching insurance renewal are being urged to look past the headline premium and compare excess levels, the amount they would pay.
Homeowners approaching insurance renewal are being urged to look past the headline premium and compare excess levels, the amount they would pay themselves towards any claim, before signing up for another year. A policy with a strikingly low price often carries a high compulsory excess, and voluntary excesses added during an online checkout can quietly raise the total further. Consumer groups suggest a simple test: if a claim for a burst pipe or a stolen bicycle would leave you paying most of the bill yourself, the policy is cheaper in a way that may not help when it matters. Renewal letters are required to show last year’s price, making comparison easier than it once was, yet many households still auto-renew while juggling busier problems. Brokers advise checking three things in the same sitting: the excess for escape of water, which is often set separately and higher; whether outbuildings and garden items are included; and the single-item limit for valuables, which catches out owners of laptops, watches and instruments more than any other clause.
What the Evidence Shows
Shopping around has become less painful than its reputation suggests. Comparison tools can hold a household’s details for repeat quotes, and insurers increasingly price the same cover quite differently, so an hour’s work before the deadline regularly saves meaningful money. Advisers warn, though, against trimming cover that matches real risks just to win the comparison table: underinsuring the rebuild cost of a home, for example, can reduce payouts proportionally even on partial claims. The excess decision itself is a balance. Raising it lowers premiums and suits households with a healthy emergency fund who expect to claim rarely; keeping it low costs more each year but protects a tight budget from a sudden bill. What matters is that the choice is made deliberately, at renewal, with the figures in front of you, rather than inherited from a form completed years ago in a hurry. As one broker puts it, insurance is the only product people buy hoping never to use, which is exactly why its small print deserves one calm reading a year. Reporting and analysis from sources such as World Bank track the same developments, and specialists following homeowners comparing insurance excess levels at renewal say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, homeowners comparing insurance excess levels at renewal matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for homeowners comparing insurance excess levels at renewal hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
Business
Cold Storage Is Becoming the Sensible Default for Long-Term Holders
Investors who plan to hold digital assets for years rather than weeks are increasingly moving them away from internet connected accounts and into.
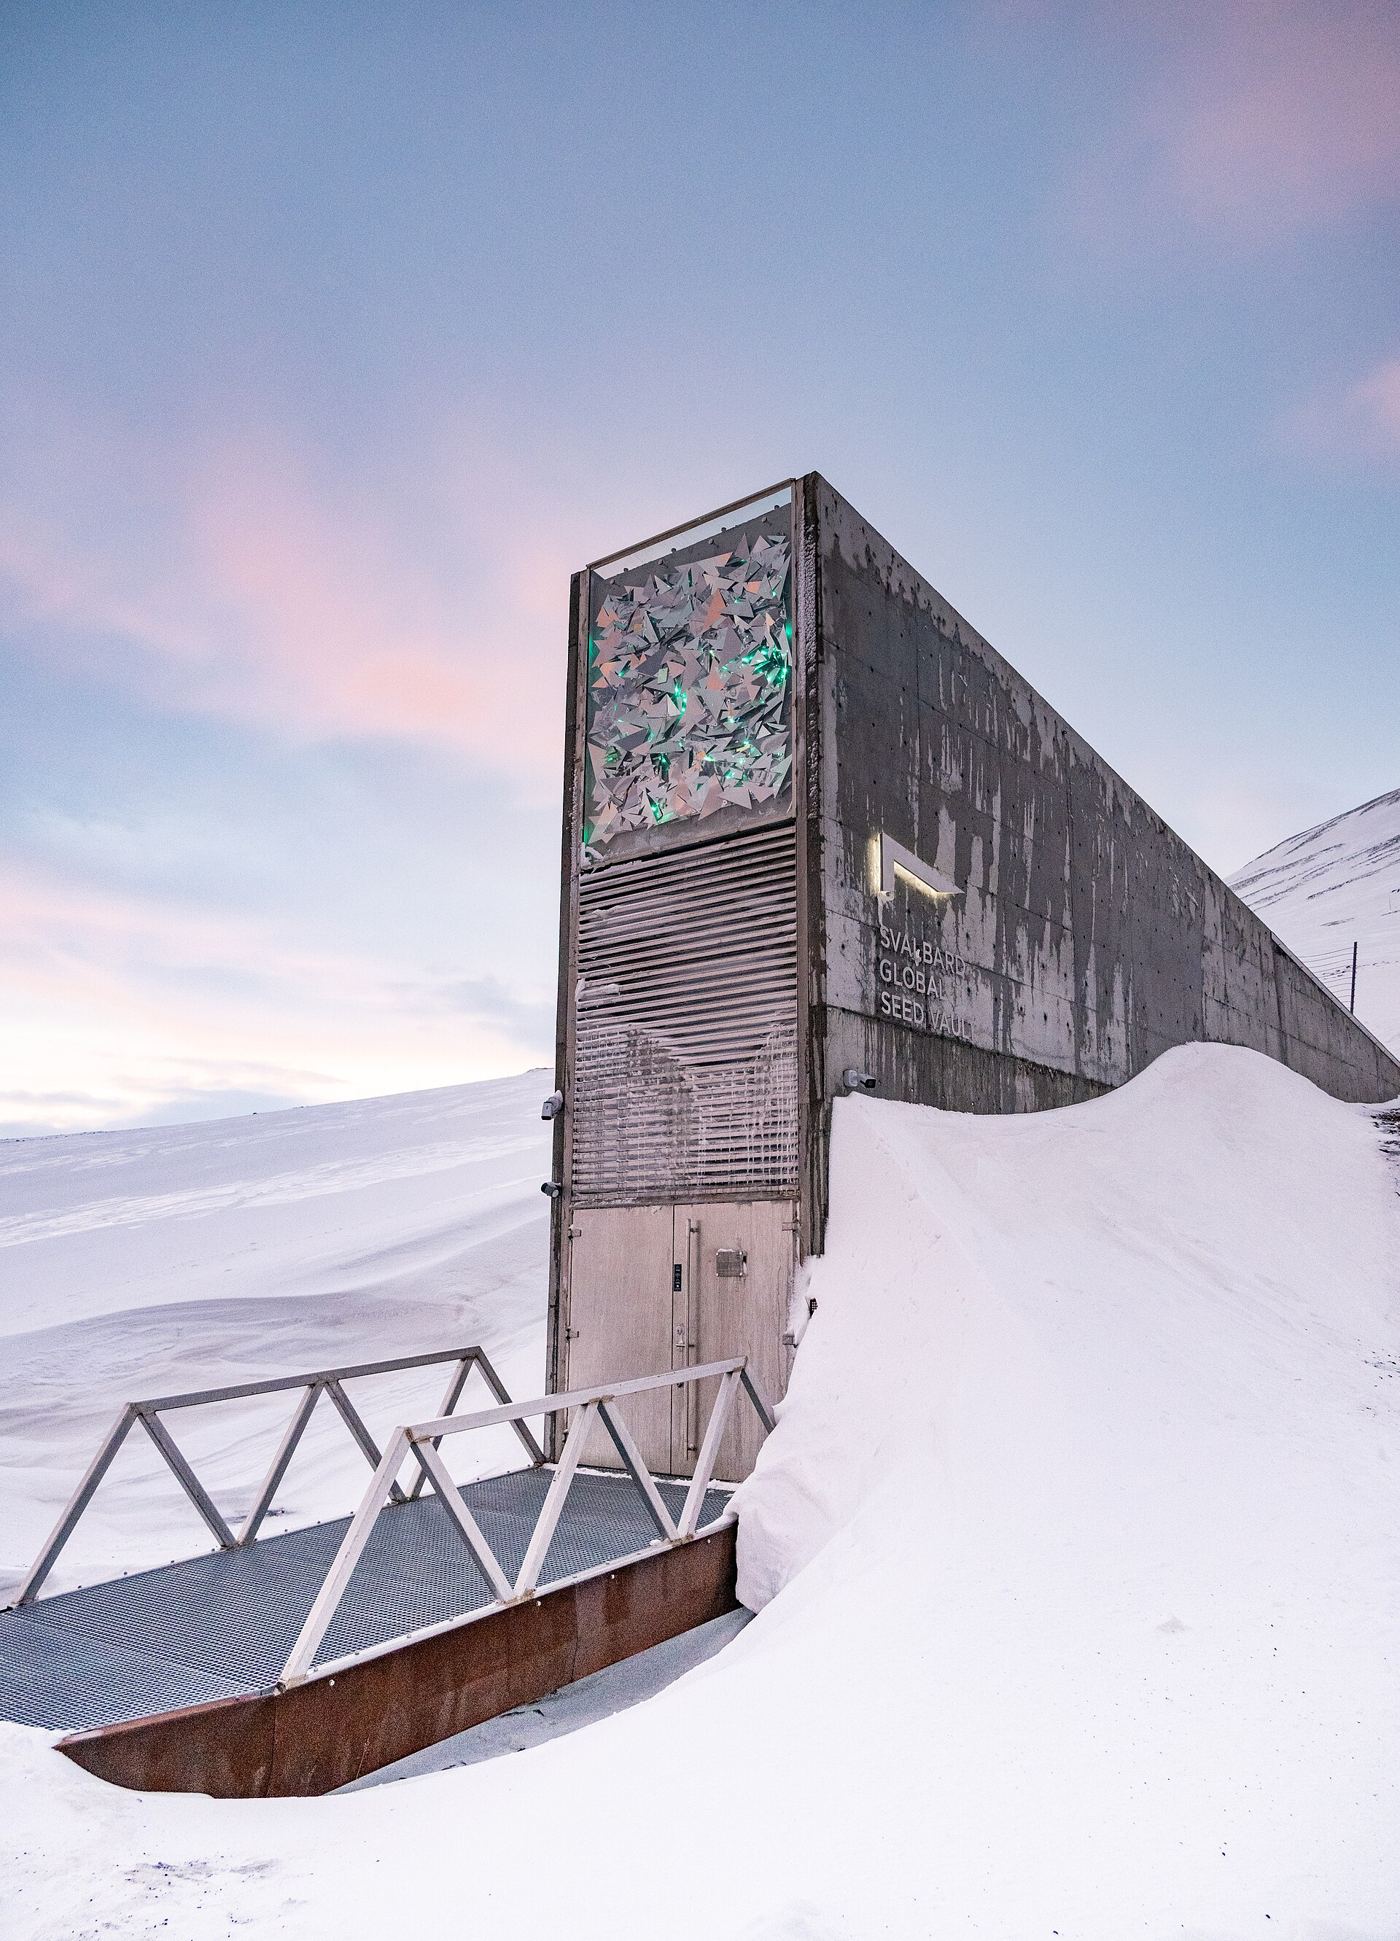
Investors who plan to hold digital assets for years rather than weeks are increasingly moving them away from internet connected accounts and into cold storage. Keeping private keys offline, on a dedicated device or secure backup, removes many of the everyday risks that come from phishing, malware, and compromised passwords. The approach suits long term holders precisely because they do not need instant access for frequent trading. What they need instead is confidence that their holdings will still be there, untouched, when they eventually return. Security specialists describe cold storage less as an advanced technique and more as basic hygiene for anyone holding meaningful value over long periods.
What the Evidence Shows
Setting it up well involves more than buying a device and transferring funds in a hurry. Users are advised to buy hardware only from trusted sources, practise the recovery process with a small amount first, and store backup phrases in separate, secure locations. Inheritance planning is also entering the conversation, since assets that only one person can access may be lost to their family if something happens to them. Clear, safely stored instructions can prevent that outcome without exposing keys during everyday life. Cold storage does demand patience and care, and mistakes during setup can be unforgiving. Handled properly, though, it offers the calmest form of ownership available. Reporting and analysis from sources such as European Central Bank track the same developments, and specialists following offline storage for long term say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a sector being absorbed, piece by piece, into the regulated financial mainstream. Work on offline storage for long term now happens under licensing regimes, audit expectations and consumer-protection rules that would have been unrecognisable a few years ago. Long-standing participants are divided between relief at the legitimacy and regret for the experiment’s wilder freedoms.
What Happens Next
What happens next for offline storage for long term will be shaped by the interaction of regulation, market appetite and the sector’s own capacity for self-inflicted wounds. The infrastructure is more professional than it was, the rules are clearer, and the remaining question is whether growth can stay boring. Participants with the longest memories say boring would be the real milestone. You can follow related developments in our coverage of crypto.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
Business
Investors Watch Earnings Season for Signs of Consumer Strength
Investors are watching the latest earnings season closely for evidence about consumer spending, business costs, and demand for technology and travel.
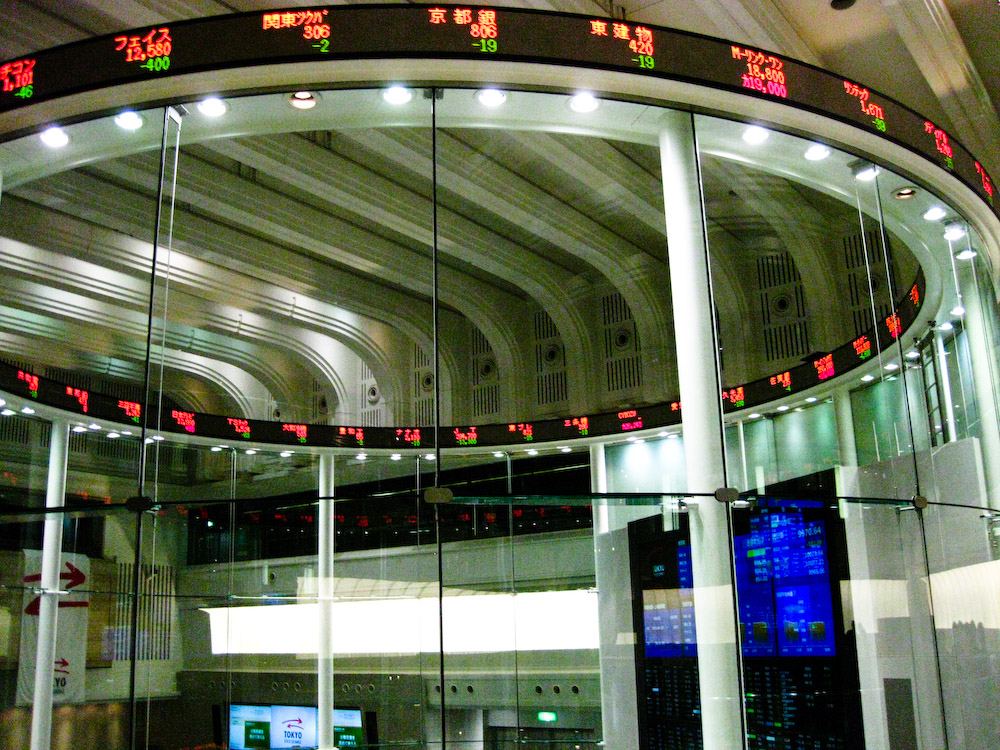
Investors are watching the latest earnings season closely for evidence about consumer spending, business costs, and demand for technology and travel. Company reports offer more than headline profits; guidance about hiring, prices, and future orders helps markets judge whether growth is broadening or narrowing. Mixed results can move individual shares sharply, even when wider indexes appear calm during the trading day for most observers. Observers say the pattern is becoming clearer as more real world examples are documented and compared carefully over time.
What the Evidence Shows
Analysts caution against reading too much into a single quarter, especially when one off charges or currency movements distort comparisons. Long term investors often focus on cash flow, debt levels, and whether management explanations match earlier promises. Diversification remains a practical defence against surprises in any one sector. Earnings season is most useful as a progress check on a plan, not as a prompt for rushed decisions. Taken together, these steps point toward practical progress that can be measured, shared, and improved by others facing similar challenges. Reporting and analysis from sources such as World Bank track the same developments, and specialists following earnings season signals say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, earnings season signals matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for earnings season signals hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.

Homeowners Compare Insurance Excess Levels Before Renewal Deadlines

Families Track Subscriptions In A Shared Notebook To Cut Waste

Developers Adopt Review Checklists That Catch Accessibility Faults Early

Council Service Centres Move Paper Forms Online While Keeping Counter Help

Viewing Weekends Help Renters Compare New Homes Calmly

Humanoid Robots Learn Warehouse Tasks in Careful Laboratory Trials

Park Entrances Get Clearer Signs to Help First-Time Visitors

14 ExtraTorrent Proxy | Unblock All Extratorrents Sites

Facebook VIP Cover Photos

Jay Bhim Bio For Instagram

क्षत्रिय Bio For Instagram in Hindi

How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide

Instagram Bio Marathi

Islamic Bio For Instagram

 Tech2 years ago
14 ExtraTorrent Proxy | Unblock All Extratorrents Sites
- Facebook Bio2 years ago
Facebook VIP Cover Photos
- Instagram Bio2 years ago
Jay Bhim Bio For Instagram
- Instagram Bio2 years ago
क्षत्रिय Bio For Instagram in Hindi
- LATEST NEWS2 years ago
How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide
- Instagram Bio2 years ago
Instagram Bio Marathi
- Instagram Bio2 years ago
Islamic Bio For Instagram
- Tech2 years ago
Socialmediagirls Forums: A Great Way to Find New Friends