Business
Home Insurance Costs Climb as Climate Claims Rise
Home insurance premiums are climbing in many regions as insurers pay out more for damage linked to storms, floods and wildfires, passing the.

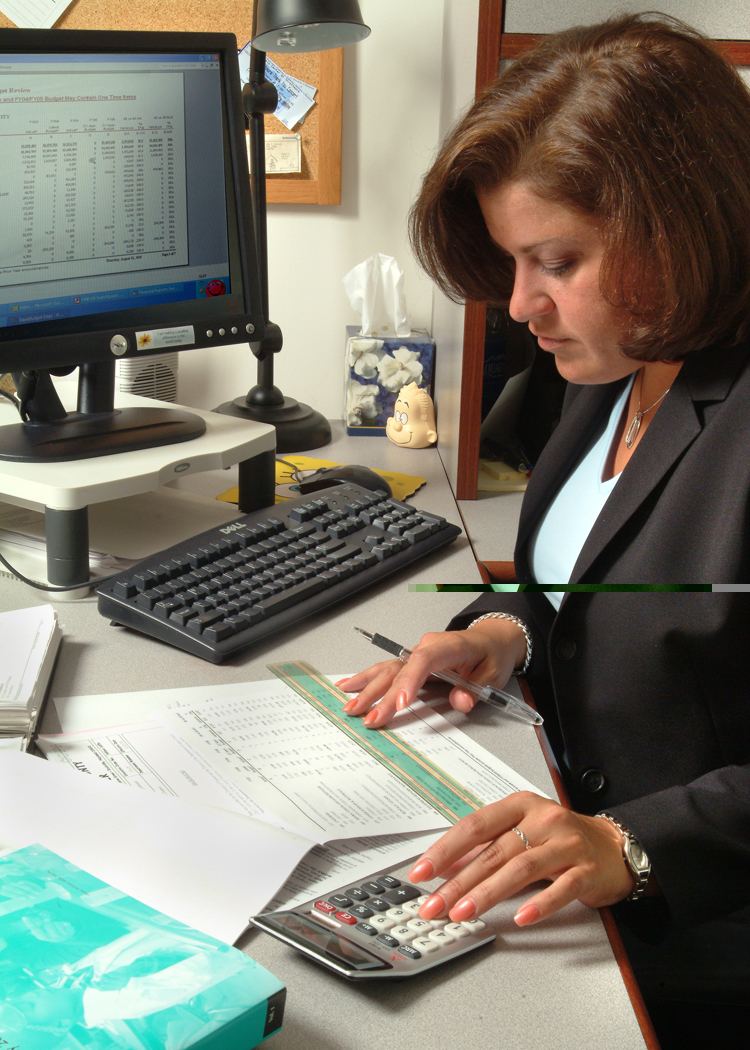
Home insurance premiums are climbing in many regions as insurers pay out more for damage linked to storms, floods and wildfires, passing the higher cost of claims on to policyholders. Industry data shows that weather-related losses have risen sharply over the past decade, with some insurers reporting that a single severe season can wipe out years of underwriting profit. In the worst-affected areas, some companies have stopped writing new policies altogether, leaving homeowners to search for cover from specialist providers at much higher prices. Consumer groups warn that rising premiums are forcing some households to cut cover or go without insurance, a risky choice that can leave families unable to rebuild after a disaster. Governments are under pressure to respond, with proposals ranging from subsidised reinsurance to stricter building standards in high-risk zones. For now, homeowners are being urged to review their policies carefully, since the cheapest option may not cover the risks that matter most.
What the Evidence Shows
Insurers say the increases reflect a genuine change in risk, not opportunism. Reinsurance, the cover that insurers buy to protect themselves against large losses, has also become more expensive, and those costs flow through to household premiums. Some insurers are offering discounts for homes with flood defences, fire-resistant materials or storm shutters, hoping to encourage resilience rather than simply raising prices. Technology is playing a role too, with satellite imagery and detailed flood maps allowing insurers to price risk at the level of individual properties. Critics argue that the market is failing households in high-risk areas, and that without government support, insurance could become unaffordable for the people who need it most. Several countries are examining public-private schemes that share the cost of extreme events, similar to existing arrangements for terrorism or flood risk. Until such schemes arrive, experts advise homeowners to check exclusions, compare quotes annually and document their possessions, so that a claim is not rejected on a technicality. Reporting and analysis from sources such as World Bank track the same developments, and specialists following home insurance and climate claims say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, home insurance and climate claims matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for home insurance and climate claims hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.


Business
Gig Workers Build Financial Buffers for Irregular Income
Gig workers are building financial buffers to cope with irregular income, as delivery driving, freelancing and short-term contracts become a.
Gig workers are building financial buffers to cope with irregular income, as delivery driving, freelancing and short-term contracts become a larger share of the workforce. Unlike salaried employees, gig workers can see their earnings swing sharply from week to week, with quiet periods, unpaid waiting time and no sick pay to fall back on. Financial advisers say the first priority is a buffer that covers essential bills during a slow month, built up during busier periods when earnings are higher. Many workers use a simple rule: set aside a fixed share of every payment, often around a fifth, split between tax, savings and a rainy-day fund. Digital banking tools help, with some accounts automatically sorting incoming payments into separate pots for tax, bills and spending. The approach requires discipline, but workers who manage it say the buffer transforms a bad week from a crisis into an inconvenience, and gives them the freedom to turn down poorly paid jobs.
What the Evidence Shows
The challenges for gig workers go beyond saving, and support is slowly catching up. Tax is a common worry, since no employer deducts it, and workers must track their own earnings and set money aside for the annual bill. Some use accounting apps that estimate tax as they earn, while others open a separate account solely for tax money so it is never spent by accident. Pension saving is another gap, with many gig workers saving nothing for retirement, and several countries are testing schemes that let platforms contribute to a worker’s pension automatically. Insurance is also patchy: income protection and public liability cover exist, but many workers do not know about them or find the cost hard to justify. Financial educators say the basics are the same as for anyone, but irregular income makes those habits harder to keep, and tools that automate the split are proving the most popular solution. Reporting and analysis from sources such as World Bank track the same developments, and specialists following gig worker financial planning say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, gig worker financial planning matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for gig worker financial planning hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
Business
Blockchain Networks Promise Faster Settlements for Everyday Payments
Blockchain networks promise faster settlements for everyday payments, offering a way to move money between people and businesses in minutes rather.
Blockchain networks promise faster settlements for everyday payments, offering a way to move money between people and businesses in minutes rather than days. The technology works as a shared digital ledger, maintained by many computers at once, so that a payment can be recorded and verified without passing through a chain of intermediaries that each add delay and cost. Supporters say the greatest benefit may be for cross-border payments, where sending money abroad has long been slow and expensive, and for small businesses waiting days for card payments to clear. Several payment firms and banks are now testing blockchain settlement alongside their existing systems, and early trials suggest the technology can cut both the time and the fees involved in moving money. For businesses that trade across borders, the savings are welcome, because fees and delays on international payments have long eaten into thin margins and slow cash flow for smaller exporters most of all.
What the Evidence Shows
Sceptics urge caution, noting that blockchain systems have faced problems with energy use, security breaches and confusing user experiences, and that regulation is still catching up in many countries. A faster payment is only useful if it is also safe, they argue, and consumers should understand that transactions on some networks cannot be reversed if money is sent to the wrong address. Businesses considering the technology should check the costs, the reliability of the network and whether their customers actually want it, rather than adopting it for novelty. Regulators are working on rules that protect consumers while allowing genuine innovation to develop. The promise is real, experts agree, but blockchain will earn its place in everyday payments only when it proves itself cheaper, faster and safer than the systems people already trust. Pilot projects remain small, but supporters say the technology is maturing and wider adoption could follow within a few years. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following blockchain payment settlement say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by blockchain payment settlement are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with blockchain payment settlement will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
Business
Savers Compare Fixed-Term Accounts as Rates Diverge Between Banks
Savers are comparing fixed-term accounts more carefully as the rates offered by banks and building societies diverge, with the gap between the.
Savers are comparing fixed-term accounts more carefully as the rates offered by banks and building societies diverge, with the gap between the best and average deals widening for one, two and five year terms. Fixed-term accounts pay a set rate in exchange for leaving money untouched for an agreed period, which makes them attractive to people saving for a known future cost who do not need immediate access. The widening spread means that accepting a familiar provider default offer can leave a meaningful amount of interest unclaimed over a full term, particularly on larger balances. Comparison services report that savers are also paying closer attention to how interest is paid, whether monthly or at maturity, and to what happens if money must be withdrawn early. Some accounts prohibit withdrawals entirely, while others allow them with a penalty measured in days of interest. Financial educators say understanding those terms matters as much as the headline rate, because circumstances can change during a fixed period lasting several years.
What the Evidence Shows
Advisers suggest savers start by separating money into categories: an accessible emergency fund, savings needed within a known timeframe and longer-term funds that can genuinely be locked away. Only the last two categories are usually candidates for fixed terms, and staggering maturity dates across different terms can provide regular points at which money becomes available again. Tax treatment is another consideration, since interest may be taxable depending on individual circumstances and the type of account used, including tax-free wrappers where available. Savers are also reminded to check deposit protection limits and whether several brands share a single banking licence, which can affect how much protection applies across accounts with related providers. Providers, for their part, adjust fixed rates according to their own funding needs, which is one reason similar accounts can be priced quite differently at the same moment. Shopping around at maturity is equally important, because balances left in place may move to a much lower rate. A short review before committing can make the difference between a fair return and an unnecessarily poor one. Reporting and analysis from sources such as World Bank track the same developments, and specialists following diverging fixed-term savings rates say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, diverging fixed-term savings rates matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for diverging fixed-term savings rates hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.

Gig Workers Build Financial Buffers for Irregular Income

Blockchain Networks Promise Faster Settlements for Everyday Payments

Home Insurance Costs Climb as Climate Claims Rise

Savers Compare Fixed-Term Accounts as Rates Diverge Between Banks

Banks Test Shared Ledgers to Speed Cross-Border Supplier Payments

Households Photograph Valuables to Speed Up Home Insurance Claims

Local Credit Unions Expand Low-Cost Loans for Home Repairs

14 ExtraTorrent Proxy | Unblock All Extratorrents Sites

Facebook VIP Cover Photos

Jay Bhim Bio For Instagram

क्षत्रिय Bio For Instagram in Hindi

How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide

Instagram Bio Marathi

Islamic Bio For Instagram

 Tech2 years ago
14 ExtraTorrent Proxy | Unblock All Extratorrents Sites
- Facebook Bio2 years ago
Facebook VIP Cover Photos
- Instagram Bio2 years ago
Jay Bhim Bio For Instagram
- Instagram Bio2 years ago
क्षत्रिय Bio For Instagram in Hindi
- LATEST NEWS2 years ago
How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide
- Instagram Bio2 years ago
Instagram Bio Marathi
- Instagram Bio2 years ago
Islamic Bio For Instagram
- Tech2 years ago
Socialmediagirls Forums: A Great Way to Find New Friends