Business
Young Drivers Cut Car Insurance Costs With Telematics
Young drivers pay the highest car insurance premiums of any age group, often thousands of pounds a year, because insurers see them as the riskiest.

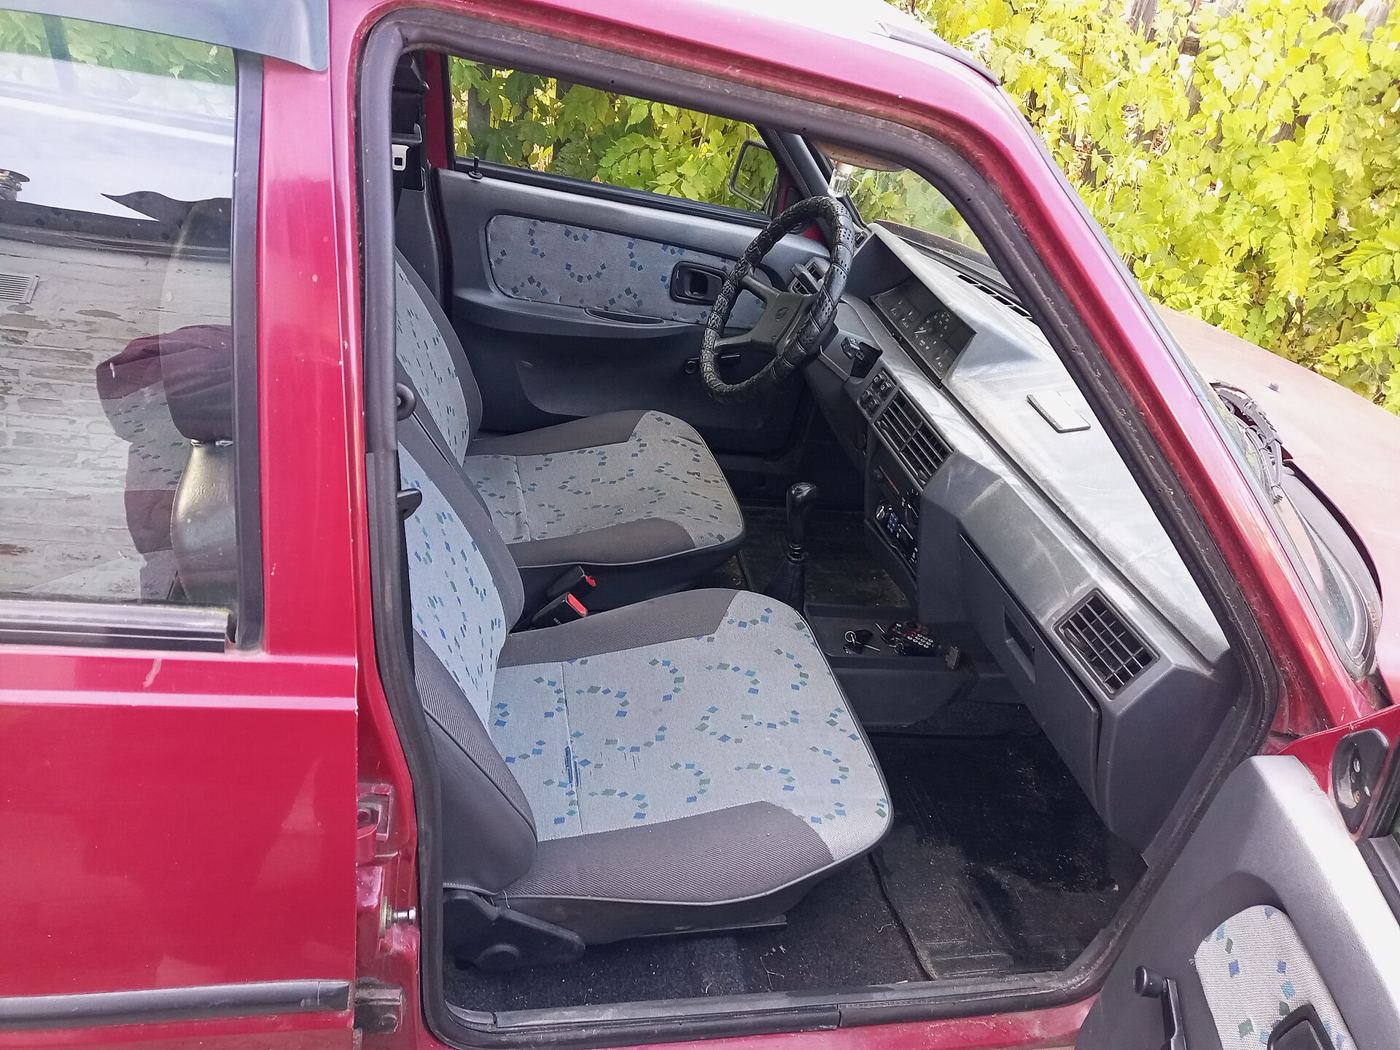
Young drivers pay the highest car insurance premiums of any age group, often thousands of pounds a year, because insurers see them as the riskiest customers on the road. A small device or phone app known as telematics, sometimes called a black box, is changing that calculation. The device records how the car is driven, tracking speed, braking, cornering, mileage and the time of day, and sends the data to the insurer. A careful young driver who avoids late-night trips, brakes gently and keeps within speed limits can earn a discount at renewal, sometimes cutting the premium by a large amount. Insurers say the data lets them price each driver on their own behaviour rather than on the average for their age group. For many young drivers, the box is the difference between affording a car and leaving it parked, and some policies now offer a discount after just a few months of safe driving.
What the Evidence Shows
The trade-off is privacy, and not every driver is comfortable with it. The insurer knows where the car goes and when, and some drivers worry about the data being used to raise premiums after a single bad journey or being shared with other companies. Insurers insist the data is used only to set the price, and that a driver can see their own scores and learn where to improve. The devices have also been credited with making young drivers safer, since knowing that every harsh brake is recorded encourages gentler driving. Some policies add curfews, charging more for driving late at night, which critics say punishes young workers on night shifts. Supporters reply that the statistics back the curfew, since crashes are far more likely after midnight. As the technology spreads, insurers are also offering telematics to older drivers who want a discount for low mileage. Reporting and analysis from sources such as World Bank track the same developments, and specialists following young drivers cutting car insurance costs with telematics say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, young drivers cutting car insurance costs with telematics matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for young drivers cutting car insurance costs with telematics hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
Business
First-Time Buyers Save for a Deposit One Payday at a Time
First-time buyers are saving for a deposit one payday at a time, turning a goal that once felt impossible into a steady monthly habit.
First-time buyers are saving for a deposit one payday at a time, turning a goal that once felt impossible into a steady monthly habit. A deposit is the biggest barrier to buying a first home, with the average first-time buyer needing tens of thousands of pounds before a lender will even consider an application. Money advisers say the savers who succeed are rarely the ones who save the most in a single month, but the ones who save a fixed amount every payday, automatically, before the money can be spent. A separate savings account, ideally one that pays a decent rate and is hard to dip into, makes the habit stick, and government schemes such as a Lifetime ISA can add a bonus to the pot. Many savers also cut a specific cost, such as takeaways or a streaming bundle, and move that exact amount into the deposit fund. The progress feels slow at first, they say, then suddenly the balance looks like a real deposit. For first-time buyers, the habit matters more than the headline figure.
What the Evidence Shows
Experts recommend a few practical steps: set a target and a date, check how much can be borrowed at different deposit sizes, and keep an eye on schemes for first-time buyers that may change the amount needed. A regular review, even quarterly, keeps motivation up and shows whether the plan is on track. Savers are advised to keep the deposit fund separate from emergency savings, so a broken car does not raid the house fund. It is also worth checking the credit report early, since a poor score can delay a mortgage even with a deposit saved. Parents and family sometimes help, and advisers say any gift should be documented, since lenders ask where the deposit came from. For buyers who keep going, the payoff is real: a deposit saved, a mortgage offered, and the front door of a first home. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following saving for a house deposit say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by saving for a house deposit are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with saving for a house deposit will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
Business
Green Bonds Fund the Energy Transition in Emerging Economies
Green bonds have become one of the main ways emerging economies raise money for clean energy, with governments and companies selling debt that is.
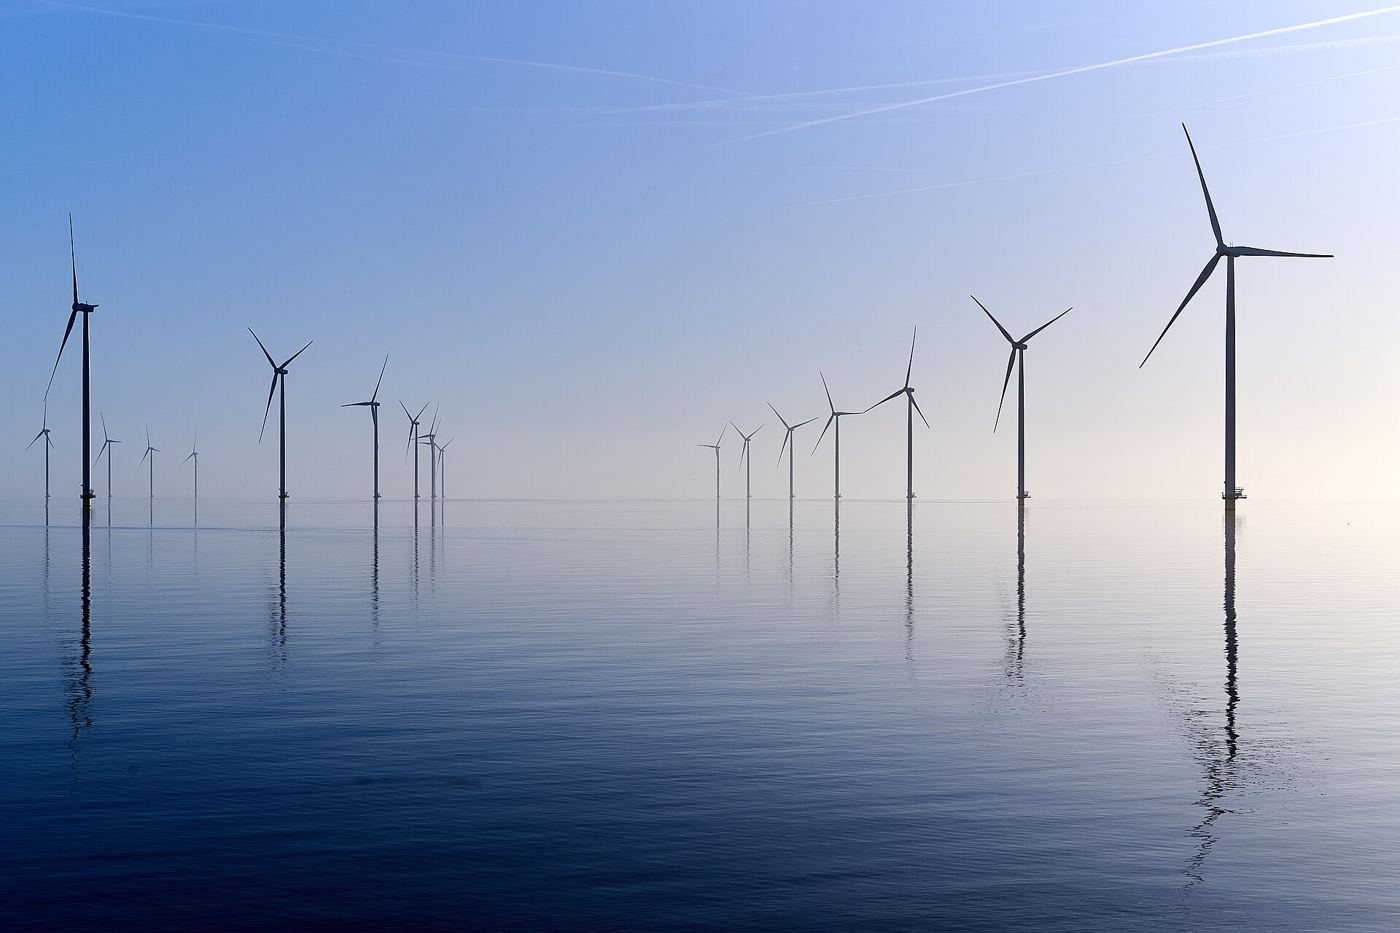
Green bonds have become one of the main ways emerging economies raise money for clean energy, with governments and companies selling debt that is earmarked for wind farms, solar plants, clean transport and energy-efficient buildings. The market has grown rapidly, as investors looking for both returns and environmental impact buy the bonds, and as borrowers welcome a new source of funding beyond traditional bank loans. For a developing country, a green bond can finance a solar plant that would otherwise wait years for funding, bringing power to homes and businesses sooner. The bonds also carry a discipline: the borrower must report on how the money was spent and what it achieved, which gives investors a clearer view than a general loan. Supporters say the market shows that finance can move quickly when the purpose is clear and the returns are sound. New issues arrive regularly now, and the range of borrowers keeps widening each year.
What the Evidence Shows
The market still faces questions about standards and scale. Investors want to be sure that a bond labelled green genuinely funds clean projects, and independent checks are becoming a normal part of the process. Currency risk is another issue, since many emerging-market borrowers raise money in dollars or euros but earn revenue in local currency, so a sharp fall in the exchange rate can make repayment harder. Some countries are now issuing green bonds in their own currency, with development banks helping to attract buyers. Analysts say the amounts raised are still small compared with the investment needed to transform energy systems, but the market is growing each year. If standards hold and costs fall, green bonds could become a routine part of how emerging economies pay for cleaner power. Reporting and analysis from sources such as World Bank track the same developments, and specialists following green bond energy transition finance say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, green bond energy transition finance matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for green bond energy transition finance hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
Business
Savers Compare Easy-Access Rates as Banks Adjust Interest Offers
Savers are comparing easy-access rates as banks adjust their interest offers, with many discovering their money has sat in an account paying far.
Savers are comparing easy-access rates as banks adjust their interest offers, with many discovering their money has sat in an account paying far less than newer deals. Easy-access accounts are popular because the money can be withdrawn at any time, yet that convenience often comes with a rate that falls quietly after an introductory bonus ends. Consumer groups say the gap between the best and worst easy-access rates remains wide, so a few minutes spent comparing can earn a saver considerably more interest over a year without any extra risk. Comparison sites make the search simple, showing the rate, any bonus period and the conditions attached, such as a limit on withdrawals or a minimum balance. Many savers now keep a main easy-access pot for emergencies and move the rest to a notice account or fixed-rate deal for a better return. The key, advisers say, is to check the rate at least once a year, because an account that was competitive when it was opened may no longer be.
What the Evidence Shows
Experts recommend checking whether the advertised rate includes a temporary bonus, and noting when that bonus expires so the account can be moved again if needed. Savers should also check that their money is protected by the deposit guarantee scheme, which covers savings up to a set limit per bank, and that any account they choose suits how often they need to withdraw. Splitting savings between two providers can be sensible for larger sums, and a regular saver account may suit those putting money aside each month. Banks sometimes reserve their best rates for new customers, so existing savers should not be afraid to move or to ask their current bank to match a better offer. For savers with a growing balance, advisers say, an annual rate check is one of the simplest ways to earn more from money that is already saved. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following easy-access savings rates say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by easy-access savings rates are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with easy-access savings rates will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.

Young Drivers Cut Car Insurance Costs With Telematics

First-Time Buyers Save for a Deposit One Payday at a Time

Green Bonds Fund the Energy Transition in Emerging Economies

Savers Compare Easy-Access Rates as Banks Adjust Interest Offers

Gig Workers Build Financial Buffers for Irregular Income

Blockchain Networks Promise Faster Settlements for Everyday Payments

Home Insurance Costs Climb as Climate Claims Rise

14 ExtraTorrent Proxy | Unblock All Extratorrents Sites

Facebook VIP Cover Photos

Jay Bhim Bio For Instagram

क्षत्रिय Bio For Instagram in Hindi

How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide

Instagram Bio Marathi

Islamic Bio For Instagram

 Tech2 years ago
14 ExtraTorrent Proxy | Unblock All Extratorrents Sites
- Facebook Bio2 years ago
Facebook VIP Cover Photos
- Instagram Bio2 years ago
Jay Bhim Bio For Instagram
- Instagram Bio2 years ago
क्षत्रिय Bio For Instagram in Hindi
- LATEST NEWS2 years ago
How to Fix a Redgifs Not Loading Issue: A Step-by-Step Guide
- Instagram Bio2 years ago
Instagram Bio Marathi
- Instagram Bio2 years ago
Islamic Bio For Instagram
- Tech2 years ago
Socialmediagirls Forums: A Great Way to Find New Friends